Portrait of Jonathan Kelly

Jonathan Kelly

Research Assistant·University of Cambridge

I studied mathematics and statistics, and I am mostly interested in learning new and difficult things.

About

I’m currently a research assistant at the University of Cambridge, having recently completed a Master’s in Statistics and Applied Mathematics (Part III). Before that I read Mathematics at Trinity College Dublin, and worked as a Credit Risk Consultant and Researcher at Murex.

Most of what I’ve worked on sits somewhere between probability, statistics and applications: stochastic processes, systematic trading strategies, numerical methods and diffusion models.

The projects you’ll find below are the ones I’ve enjoyed most.

Aside from maths, I spend a fair amount of time on music and sport. If you’d like to talk about any of the above, my inbox is open.

Selected projects

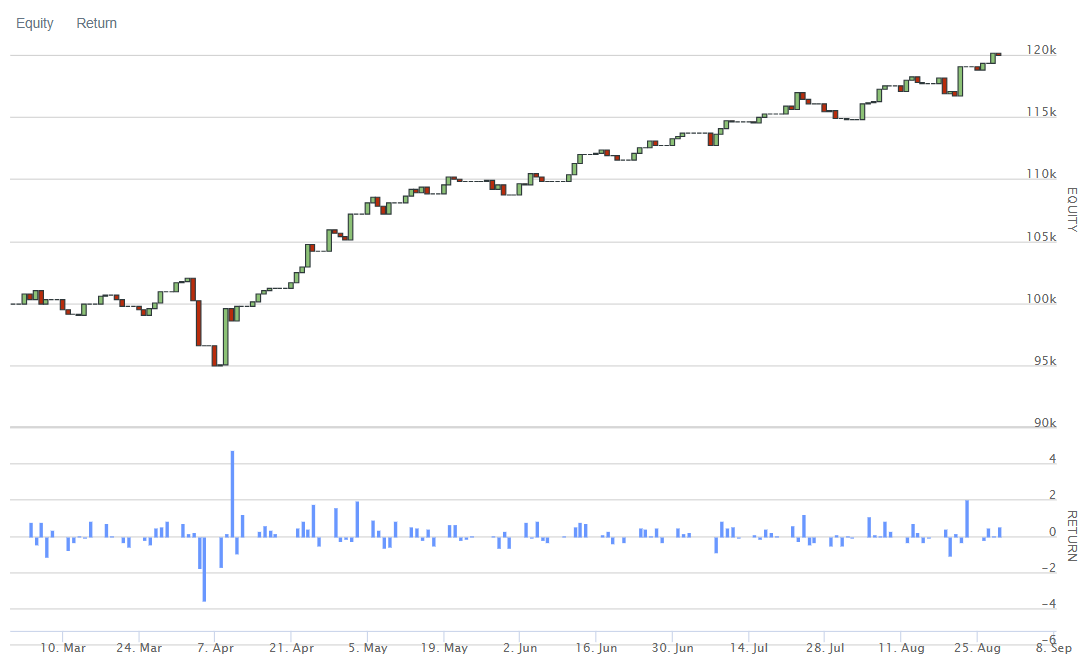
Equity curve and per-trade returns for the combined strategy backtest

Combined Defensive Allocation & Kalman Filter Pairs Strategy

A multi-strategy leveraged portfolio combining strategic gold allocation, Defensive Adaptive Asset Allocation (DAA) and market-neutral pairs trading, with the pairs leg driven by a Kalman filter on the hedge ratio.

  • Python
  • QuantConnect
  • Kalman filter
  • Pairs trading
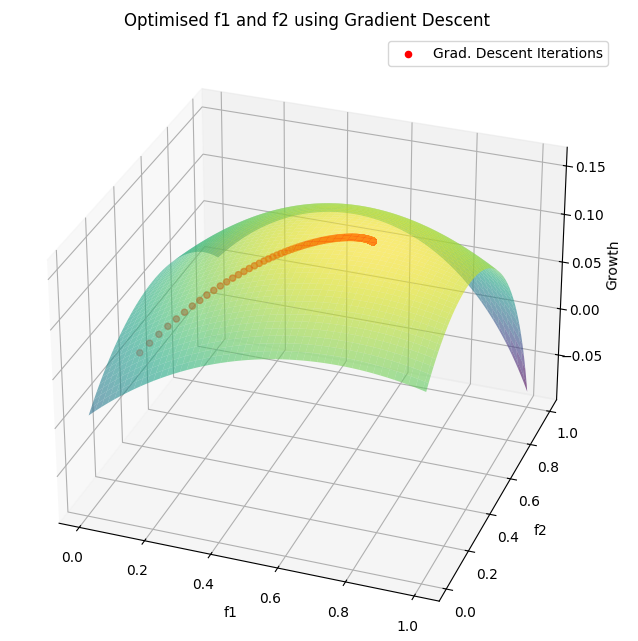
Gradient descent surface over investment fractions

Applications of the Kelly Criterion to Multiple Investment Games

Extends the Kelly criterion to a game with several simultaneous bets, then uses gradient descent to learn the fractions of wealth that maximise the long-run growth rate.

  • Python
  • Optimisation
  • Gradient descent
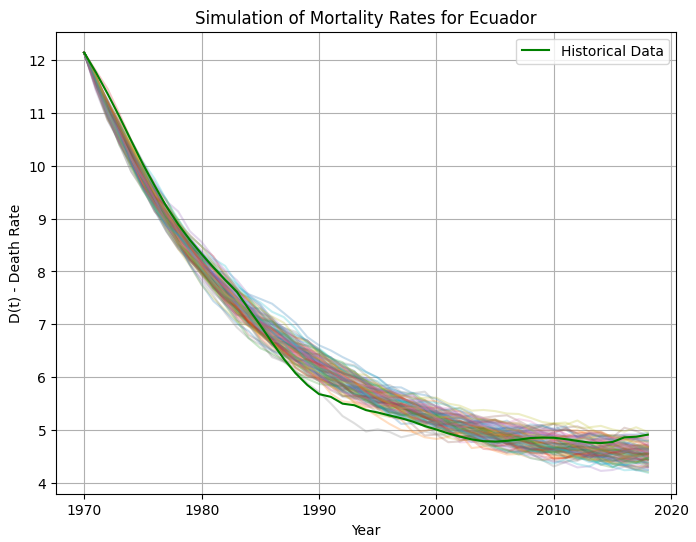
Ornstein-Uhlenbeck paths fitted to mortality rate data

Applying Stochastic Processes to Population Modelling

Fits an Ornstein–Uhlenbeck (mean-reverting) process to birth and mortality rates, calibrating the parameters and testing the mean-reversion assumption against the data.

  • Python
  • Ornstein–Uhlenbeck
  • statsmodels
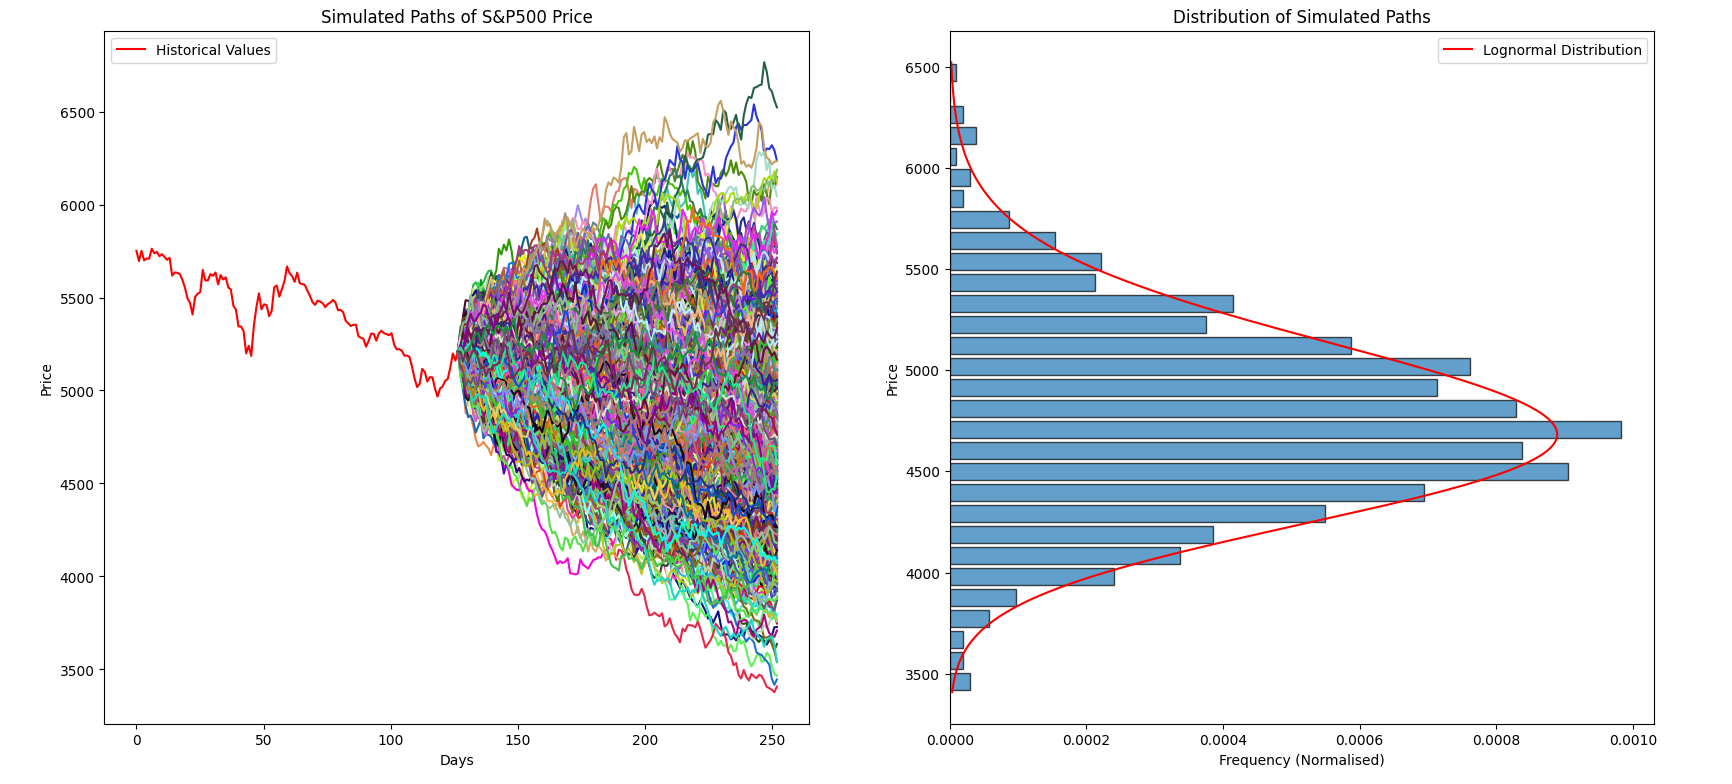
Simulated geometric Brownian motion paths against index fund prices

Applying Stochastic Processes to Financial Modelling

Uses geometric Brownian motion to simulate index fund price paths, and compares the resulting distribution of outcomes with the realised history.

  • Python
  • Geometric Brownian motion
  • Monte Carlo
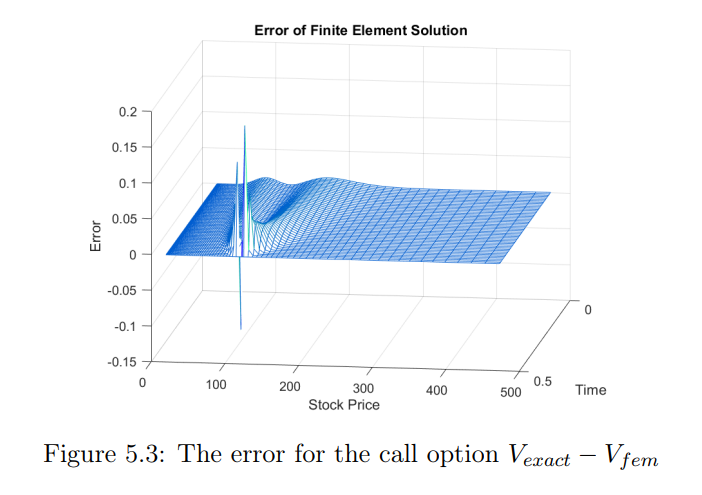
Finite element solution surface for a 2D PDE

Final year thesis: Finite Element Method for Differential Equations

Undergraduate thesis on the Finite Element Method for 1D and 2D PDEs — Poisson, heat and elliptic equations — implemented in MATLAB with numerical quadrature, then applied to the Black–Scholes equation to price European calls and puts with a focus on error analysis.

  • MATLAB
  • FEM
  • PDEs
  • Black–Scholes